Your Grandfather Did Not Buy a House Because He Worked Harder Than You
Decades ago, one basic paycheck bought a home, a car, and supported an entire family. Then the link to real money broke.
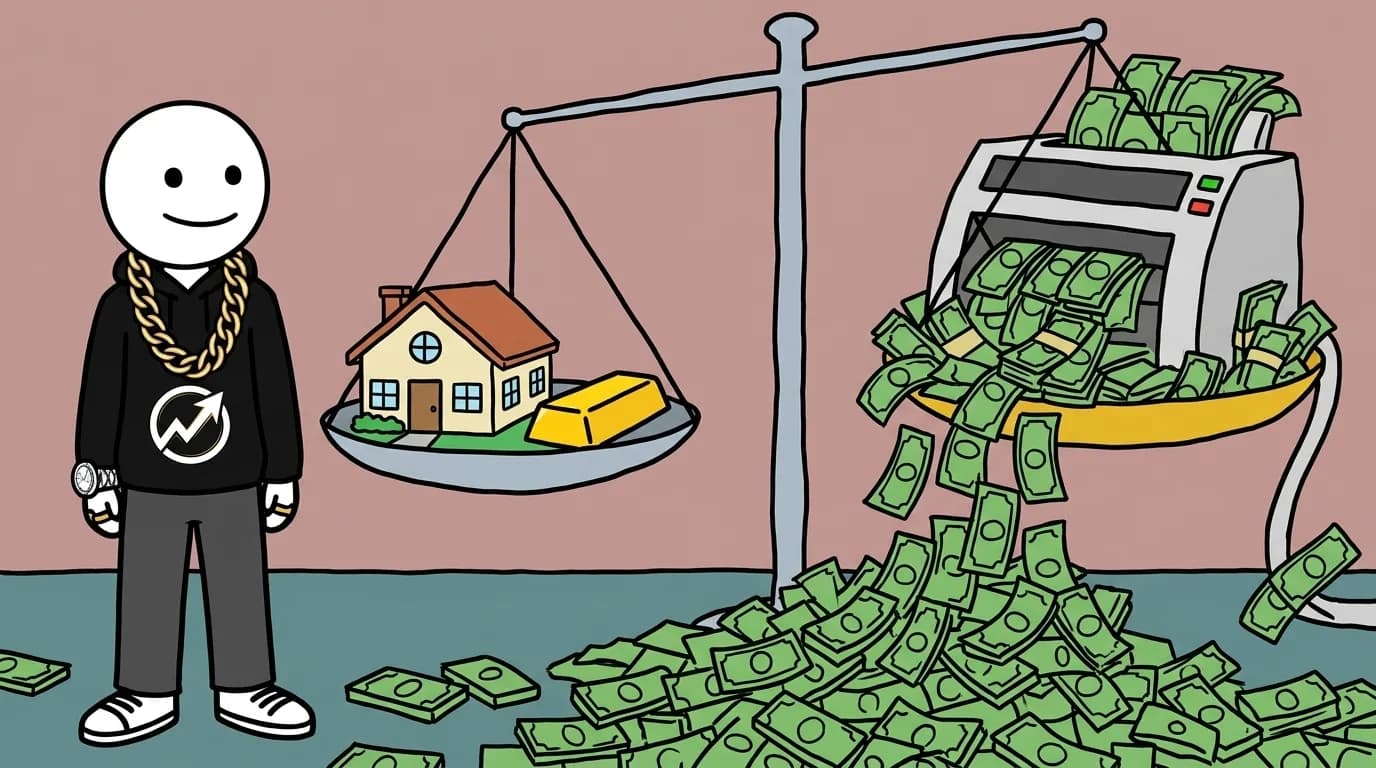
- Fifty years ago, a single modest salary easily covered a home mortgage, a vehicle, and a family of four.
- In 1971, the dollar was severed from gold, unleashing unlimited paper currency printing without fiscal restraint.
- As money supply exploded, asset prices skyrocketed while wages only tracked official consumer price baskets.
- Today, homes cost roughly double the multiple of annual income compared to 1971, forcing households into dual-income traps.
- You cannot solve a broken monetary equation with frugality alone. The only escape is owning scarce, productive assets.
Every young professional has heard the lecture. An older relative sits across the dinner table and insists that if you only stopped buying five-dollar iced lattes, packed your lunch every day, and put in an honest forty hours of grit, you too could easily buy a four-bedroom house with a two-car garage by age twenty-six.
It sounds sensible on the surface. We love stories where hard work guarantees financial triumph. But when you examine the actual numbers, the harsh truth becomes undeniable: your grandfather did not buy a house because he worked harder than you. He bought a house because the math worked.
When one paycheck ran the entire household
In the 1960s and early 1970s, the economic playbook for an average worker was straightforward. A high school graduate could land a steady job at a local manufacturer, utility company, or retail store. On that single income, they could purchase a starter home, buy a reliable family sedan, pay for yearly summer vacations, and still fund a respectable savings cushion.
One person worked forty hours a week. The other managed the home. And at the end of every month, there was money left over to put into a savings account that actually paid real interest above inflation.
Today, a household often requires two college-educated earners working fifty hours a week just to compete for a modest suburban starter home, pay astronomical childcare bills, and juggle student debt. Modern workers are not less disciplined. They are trading twice as much collective life energy for half the purchasing power.
“Modern workers are trading twice as much time for half the life. Stop blaming your work ethic: the math changed.”
August 15, 1971: the day the rules changed forever
To understand why housing detached from human labor, you have to look back to a Sunday evening in August 1971. President Richard Nixon addressed the nation on live television and announced that the United States was temporarily suspending the convertibility of the US dollar into physical gold.
Up until that evening, the world operated under the Bretton Woods monetary system. Every printed paper dollar was legally anchored to real, physical gold reserves at thirty-five dollars an ounce. That physical anchor was an iron chain on politicians and central banks. If a government wanted to spend money, it had to either collect taxes or acquire more gold. They could not simply conjure billions of new dollars out of thin air.
When Nixon closed the gold window, that chain snapped. Overnight, all global currencies became pure unbacked fiat. For the first time in human history, governments gained the ability to create infinite paper currency with zero physical limits.
The brutal home-to-income arithmetic
Look at what happened to the relationship between median home prices and median household income before and after the gold link was severed:
- 1971 Median Home Price
- ≈ $25,200
- 1971 Median Household Income
- ≈ $9,030
- 1971 Home-to-Income Multiple
- 2.8x annual salary
- 2026 Median Home Price
- ≈ $420,000
- 2026 Median Household Income
- ≈ $75,000
- 2026 Home-to-Income Multiple
- 5.6x annual salary
In 1971, a modest home cost under three times annual income. Today, it demands nearly six times annual income nationally, and often eight to ten times in major metropolitan areas.
Notice that the multiple has doubled. But the story gets even more revealing when you price a house not in depreciating paper cash, but in gold.
In 1971, gold was thirty-five dollars an ounce. A twenty-five thousand dollar house was worth roughly 720 ounces of gold. Today, 720 ounces of gold is worth over 1.9 million dollars. In terms of scarce physical money, houses did not become magically harder to build or astronomically scarce. Rather, the paper currency we measure them with lost more than eighty-five percent of its purchasing power.
Why saving cash will never bridge the gap
When you work forty hours a week and save your earnings in a commercial checking account, you are trading scarce, finite human time for something central banks can create by pressing a key on a computer.
This is why skipping morning coffee or cutting streaming subscriptions feels like emptying the ocean with a teaspoon. You cannot out-save an expanding money supply. If the money pool expands by seven to ten percent annually, holding uninvested cash guarantees that the price of real estate, stocks, and scarce commodities will outrun your salary.
Four ways to beat the broken math
- Stop measuring wealth in paper cash: Cash is an emergency buffer and an operational tool, not a long-term store of value. Measure your financial progress in units of productive assets: shares of index funds, cash-flowing properties, or equity in businesses.
- Acquire assets that benefit from monetary expansion: When governments print money, asset prices rise. By holding broad-market index funds, real estate, or scarce assets, the rising tide of liquidity lifts your balance sheet instead of drowning your purchasing power.
- Build an income stream beyond linear hours: A salary trades hours for fixed dollars. To beat inflation, you need scalable income: digital products, equity ownership, royalties, or side businesses where revenue is decoupled from time worked.
- Stop internalizing guilt over pocket change: Stop letting outdated financial advice shame you over five-dollar daily purchases. Direct your mental energy toward the decisions that actually move the needle: increasing your savings rate, boosting top-line revenue, and consistently buying productive assets.
The end
Found this useful? The fastest way to support the page is to share the reel with one person who needs it.
The Sunday Money Note
1 mindset shift and 3 actions to take that week, in your inbox every Sunday morning. A 5-minute read that starts your week with clarity instead of the Monday dread.